By the GoDay.ca Customer Education Team. GoDay is licensed to issue online payday loans in Alberta and has funded short-term loans for Calgary residents since 2012.
Key Takeaways
- In Alberta, a payday loan is an installment loan by law: it must run between 42 and 62 days and be repaid in at least two scheduled payments.
- The maximum cost of borrowing in Alberta is $14 for every $100 borrowed, including all fees, and the loan can’t exceed $1,500.
- You have a two-day cancellation period, you can repay early without a penalty, and rollovers are banned.
- Anyone offering payday loans to Calgary residents must hold an Alberta payday loan licence, including online lenders.
- GoDay accepts applications from Calgary at any hour and funds approved loans by Interac e-Transfer or direct deposit, with no store visit needed.
A payday loan in Calgary is a short-term, unsecured loan of $1,500 or less, repaid in scheduled installments over 42 to 62 days. That structure sets Alberta apart. In most provinces, a payday loan is repaid in one payment on your next payday. Alberta’s rules require every payday loan to be spread across at least two payments, which makes each withdrawal smaller and gives borrowers more time than the two-week loans common elsewhere.
Calgary households meet the same surprise expenses as anyone else: a cracked windshield after a hailstorm, a furnace repair in January, or a gap between contracts in the energy sector. This guide explains how Alberta regulates short-term loans, what one costs in dollars, who qualifies, and how to check a lender before you share any personal details.
How Installment Repayment Works for Alberta Payday Loans
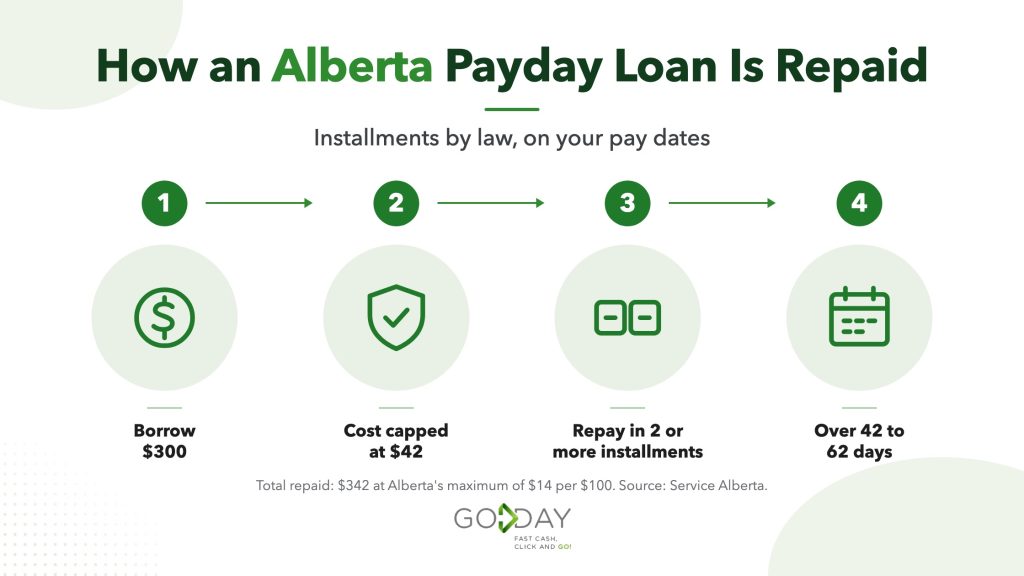
Alberta’s rules turn every payday loan into a structured installment loan. According to Service Alberta’s October 2025 payday lending tip sheet, a payday loan must have a term of between 42 and 62 days and a schedule of payments with at least two installments. Payments normally fall on days you receive your pay or other income, so the schedule follows your pay dates. If you’re paid monthly and no payday falls between day 42 and day 62, the final installment falls on another date within that window.
In practice, that means a borrower who is paid every two weeks repays over roughly three or four pay periods, and a borrower who is paid monthly repays over two. Your loan agreement lists every payment date and amount before you sign, along with the total cost of borrowing.
GoDay offers payday loans in Calgary under these rules, with loans from $100 to $1,500. The application, verification, signing, and funding all happen online.
What Are the Payday Loan Rules in Alberta?
Alberta regulates payday lending through the Consumer Protection Act and the Payday Loans Regulation. The rules below come from Service Alberta’s October 2025 consumer tip sheet and its payday loans page.
| The rule in Alberta | What it means for you in Calgary |
| The maximum cost of borrowing is $14 for every $100 borrowed. | The cap includes all fees and charges related to the loan. It has applied since January 1, 2025, when it dropped from $15. |
| The maximum loan is $1,500. | Any loan above $1,500 isn’t a payday loan under Alberta law and falls under different rules. |
| The term must be 42 to 62 days, with at least two installments. | You never repay the whole loan on a single payday. |
| Payments normally fall on a day you receive your pay or other income. | The schedule is built around your pay dates, with an exception for monthly-paid borrowers when no payday falls between day 42 and day 62. |
| You have a two-day cancellation period after you receive a copy of the agreement. | You can cancel and return the money without extra fees. If the lender isn’t open on the second day, you can cancel on its next business day. |
| Rollovers and additional credit are banned while a loan is outstanding. | A lender can’t renew your loan for a new fee or issue you more credit until the current loan is repaid. |
| Early repayment is free of any penalty. | You can repay the full balance at any time. |
| A dishonoured payment fee is capped at $20. | If a pre-authorized debit bounces, the lender can charge no more than $20. Without your fresh written consent, it can retry the debit only once. |
| Every payday lender must be licensed, including online lenders. | You can check a lender’s licence with Service Alberta before you apply. |
Alberta also limits collection practices. A payday lender can only call to collect between 7 a.m. and 10 p.m. Alberta time, can’t contact your workplace or other people to collect, and can’t publish or threaten to publish a failure to pay.
How Much Does a Payday Loan Cost in Calgary?
At the $14 per $100 maximum, the cost is predictable:
- Borrow $300 and the total cost of borrowing is $42, so you repay $342 across your scheduled installments.
- Borrow $500 and the cost is $70, so you repay $570.
- Borrow $1,000 and the cost is $140, so you repay $1,140.
Because Alberta loans run at least 42 days, the annual percentage rate is lower than on a two-week loan elsewhere, even though the dollar cost per $100 is the same. GoDay’s Alberta disclosure puts the APR on a $300 loan over 42 days at 121.67% for a borrower paid weekly, at $14 per $100 borrowed.
The cost is still high compared with other credit. If you have overdraft protection, a line of credit, or a credit card with room on it, those usually cost less for the same amount. A payday loan fits when those options aren’t available and the expense can’t wait.
GoDay doesn’t charge origination fees, processing fees, or e-Transfer fees on top of the cost of borrowing. Your own cost is shown in the loan agreement before you sign.
Who Qualifies for a Payday Loan in Calgary?
Licensed lenders in Alberta focus on income and your ability to repay. To qualify with GoDay, you need to:
- Be a Canadian resident over the age of 18.
- Have an open account at a Canadian bank or credit union.
- Get paid by direct deposit, so your income can be verified electronically.
- Have your own email address and phone number.
- Receive a steady source of income.
Steady income isn’t limited to a job. GoDay considers income from the Canada Child Benefit, Old Age Security, the Canada Pension Plan, and private pensions, subject to its lending criteria. If your income comes from another source, such as Assured Income for the Severely Handicapped (AISH) or Employment Insurance, contact GoDay to ask whether it qualifies before you apply.
GoDay’s automated decision doesn’t include a credit check, according to its FAQ, and poor credit doesn’t automatically rule out approval. Items in collections with another payday or short-term lender make approval significantly less likely. Accurate employment and banking details on the application are the best way to avoid a delay.
Online Payday Loans vs Storefront Lenders in Calgary
Calgary has both, and the same Alberta rules and cost cap apply to each. Here is how they compare on the questions borrowers ask most.
| What borrowers ask | Storefront lender in Calgary | Licensed online lender such as GoDay |
| When can I apply? | During store hours, which vary by location. | At any hour on any day, with an automated decision in seconds. |
| How is my income checked? | Usually with pay stubs, bank statements, and ID at the counter. | Electronically through instant bank verification, with no documents to upload. |
| How do I receive the money? | Cash, cheque, or transfer, depending on the store. | Interac e-Transfer, generally within 60 minutes of funding, or direct deposit. |
| What does it cost? | Up to $14 per $100 borrowed. | Up to $14 per $100 borrowed, with your cost shown in the agreement before you sign. |
| How is it repaid? | In at least two installments over 42 to 62 days. | In at least two installments over 42 to 62 days, by pre-authorized debit on your pay dates. |
The cost cap applies to both, so compare the total cost in each agreement rather than assuming one channel is cheaper. The online route saves the trip and works outside store hours. A storefront suits someone who prefers to talk to a person face to face.
How Fast Can You Get a Payday Loan in Calgary?
With GoDay, the application takes about five minutes and the automated pre-approval decision comes back within seconds. Once the loan is confirmed as funded, an Interac e-Transfer generally arrives within 60 minutes, according to GoDay’s FAQ. A direct deposit funded before 7 p.m. Eastern time on a banking day, which is 5 p.m. in Calgary, generally arrives the same day at most major banks. After that cutoff, or at smaller banks and credit unions, it generally arrives the next banking day, and weekends and payment-system holidays can push that later.
GoDay’s loan processing team works every day of the year except Christmas Day, so e-Transfer funding continues on weekends and statutory holidays when banks are closed. Our guide to weekend loans in Canada explains how the timing works on a Saturday, a Sunday, or a long weekend.
How Instant Bank Verification Replaces Paperwork
Instead of asking for pay stubs or statements, GoDay confirms income through an instant bank verification service. You sign in to your own bank through the service, which shares the deposit and account information the lender needs to confirm your income. Read the service’s consent screen and privacy policy to see what it accesses, shares, and keeps. It also means you don’t have to email your statements to anyone yourself.
What Calgary Borrowers Should Check Before Applying
Before applying, make these three checks:
- Confirm the lender’s Alberta licence. Every payday lender serving Alberta residents must be licensed, including online lenders. Use Service Alberta’s payday lender licence information to search the lender’s name, or call the Consumer Contact Centre at 1-877-427-4088.
- Refuse any request for an upfront fee. A licensed lender collects its cost through the repayment schedule. A request for an “insurance” or “processing” payment before you receive anything is a warning sign of an advance-fee scam.
- Match the installments to your budget. Payments normally fall on your pay dates, so look at what else comes out of your account on each one, such as rent, a car payment, or utilities. If the dates collide, borrow less or ask about a different schedule before signing.
If you believe a lender has broken Alberta’s rules, you can file a consumer complaint with Service Alberta’s Consumer Investigations Unit.
Alternatives Worth Checking First
A payday loan is a high-cost way to borrow, so check the cheaper routes first. Ask the creditor for more time, request a pay advance from your employer, or use overdraft protection or a line of credit if you have one. For help with a budget or existing debt, the non-profit Money Mentors offers credit counselling across Alberta.
If the expense can’t wait and those options aren’t available, GoDay’s emergency loans are designed for short, urgent cash-flow gaps. Borrow only what you need, since every $100 adds up to $14 to the cost.
How to Review Your Loan Options in Calgary With GoDay
GoDay is licensed to issue online payday loans in Alberta and has served Calgary residents since 2012, with applications accepted around the clock and funding by Interac e-Transfer or direct deposit. When an unexpected bill arrives, you can look at an Alberta installment loan as an option to spread the cost across your next few pay dates. To see what you qualify for, you can apply for a loan online in about five minutes, or read how GoDay works first. If you live elsewhere in the province, see how payday loans in Alberta work, compare other online loans, or call GoDay at 888-984-6329, seven days a week except Christmas Day.
Frequently Asked Questions
How much can I borrow with a payday loan in Calgary?
Alberta caps payday loans at $1,500, and any loan above that amount isn’t a payday loan under provincial law. Individual lenders set their own limits within that range. GoDay offers Calgary loans from $100 to $1,500, and the amount you’re approved for depends on your income and banking information. Borrowing less keeps each installment smaller, since Alberta loans are repaid in at least two payments over 42 to 62 days. Your agreement shows every payment before you sign.
What is the maximum a Calgary payday lender can charge?
The maximum is $14 for every $100 borrowed, which includes all fees and charges related to the loan. That limit has applied in Alberta since January 1, 2025, down from $15. If you repay as agreed, the most a lender can charge is $42 on a $300 loan and $70 on $500. If you miss a payment, permitted default charges apply on top, including a dishonoured-payment fee of no more than $20, and without your fresh written consent the lender can retry the debit only once.
Can I cancel a payday loan in Alberta after signing?
Yes. Alberta gives payday loan borrowers a two-day cancellation period after they receive a copy of the loan agreement. During that time, you can cancel and return the money without paying any extra fees. The lender must give you a cancellation notice form with the agreement, or you can cancel by signed letter. If the lender isn’t open for business on the second day, you can cancel on its next business day. The lender must give or send you a receipt.
Can I get a payday loan in Calgary with bad credit?
Often you can, because Alberta payday lenders weigh your income and ability to repay heavily. GoDay’s automated decision doesn’t include a credit check, according to its FAQ, and poor credit doesn’t automatically rule out approval. Items in collections with another payday or short-term lender make approval significantly less likely. Accurate income and banking details on the application give you the best chance, and no licensed lender can guarantee approval in advance.
Do I have to repay a Calgary payday loan all at once?
No. Alberta requires every payday loan to have a term of 42 to 62 days and a schedule of at least two installments, so the loan is never due in a single payment on your next payday. Installments normally fall on days you receive your pay or other income. You can still repay the full balance early at any time without a penalty, and your total cost of borrowing stays within the $14 per $100 cap.